Updated September 2026
A Lake Martin house can be a good investment, just not always in the way a spreadsheet means it. In my experience, the owners who end up happiest bought a place they use hard, held it for years, and treated any gain in value as a bonus instead of the plan. The house has to earn its keep in weekends and summers first. If a purchase only works on paper when it rents every week and sells for more in a few years, I'd slow down.
Here's how I think it through with buyers: what recent sales say about demand, what the lake itself is worth to you, what financing costs today, and the tax rules that change the math depending on how you use the place.
The Bottom Line
- Association-wide residential sales ran ahead of last year this July, per the Lake Martin Area Association of REALTORS®.
- Borrowing costs more than it did a year ago, so the monthly carry on a financed lake house is higher.
- How you use the house (personal, rental, or both) affects your federal tax treatment and can affect how Alabama assesses it for property tax.
- My read: buy for use first, choose the lot and the water carefully, and don't count on appreciation to make the numbers work.
What Lake Martin sales look like right now
The Lake Martin Area Association of REALTORS® counted 75 (Lake Martin Area Association of REALTORS, July 2026) residential sales in July 2026, up from 63 in July 2025. That's 12 more closed sales in the same month, by our math. These are association-wide totals, and they include both waterfront and off-water homes. The July 2026 bar stands clearly taller than July 2025 when you put the two months side by side.
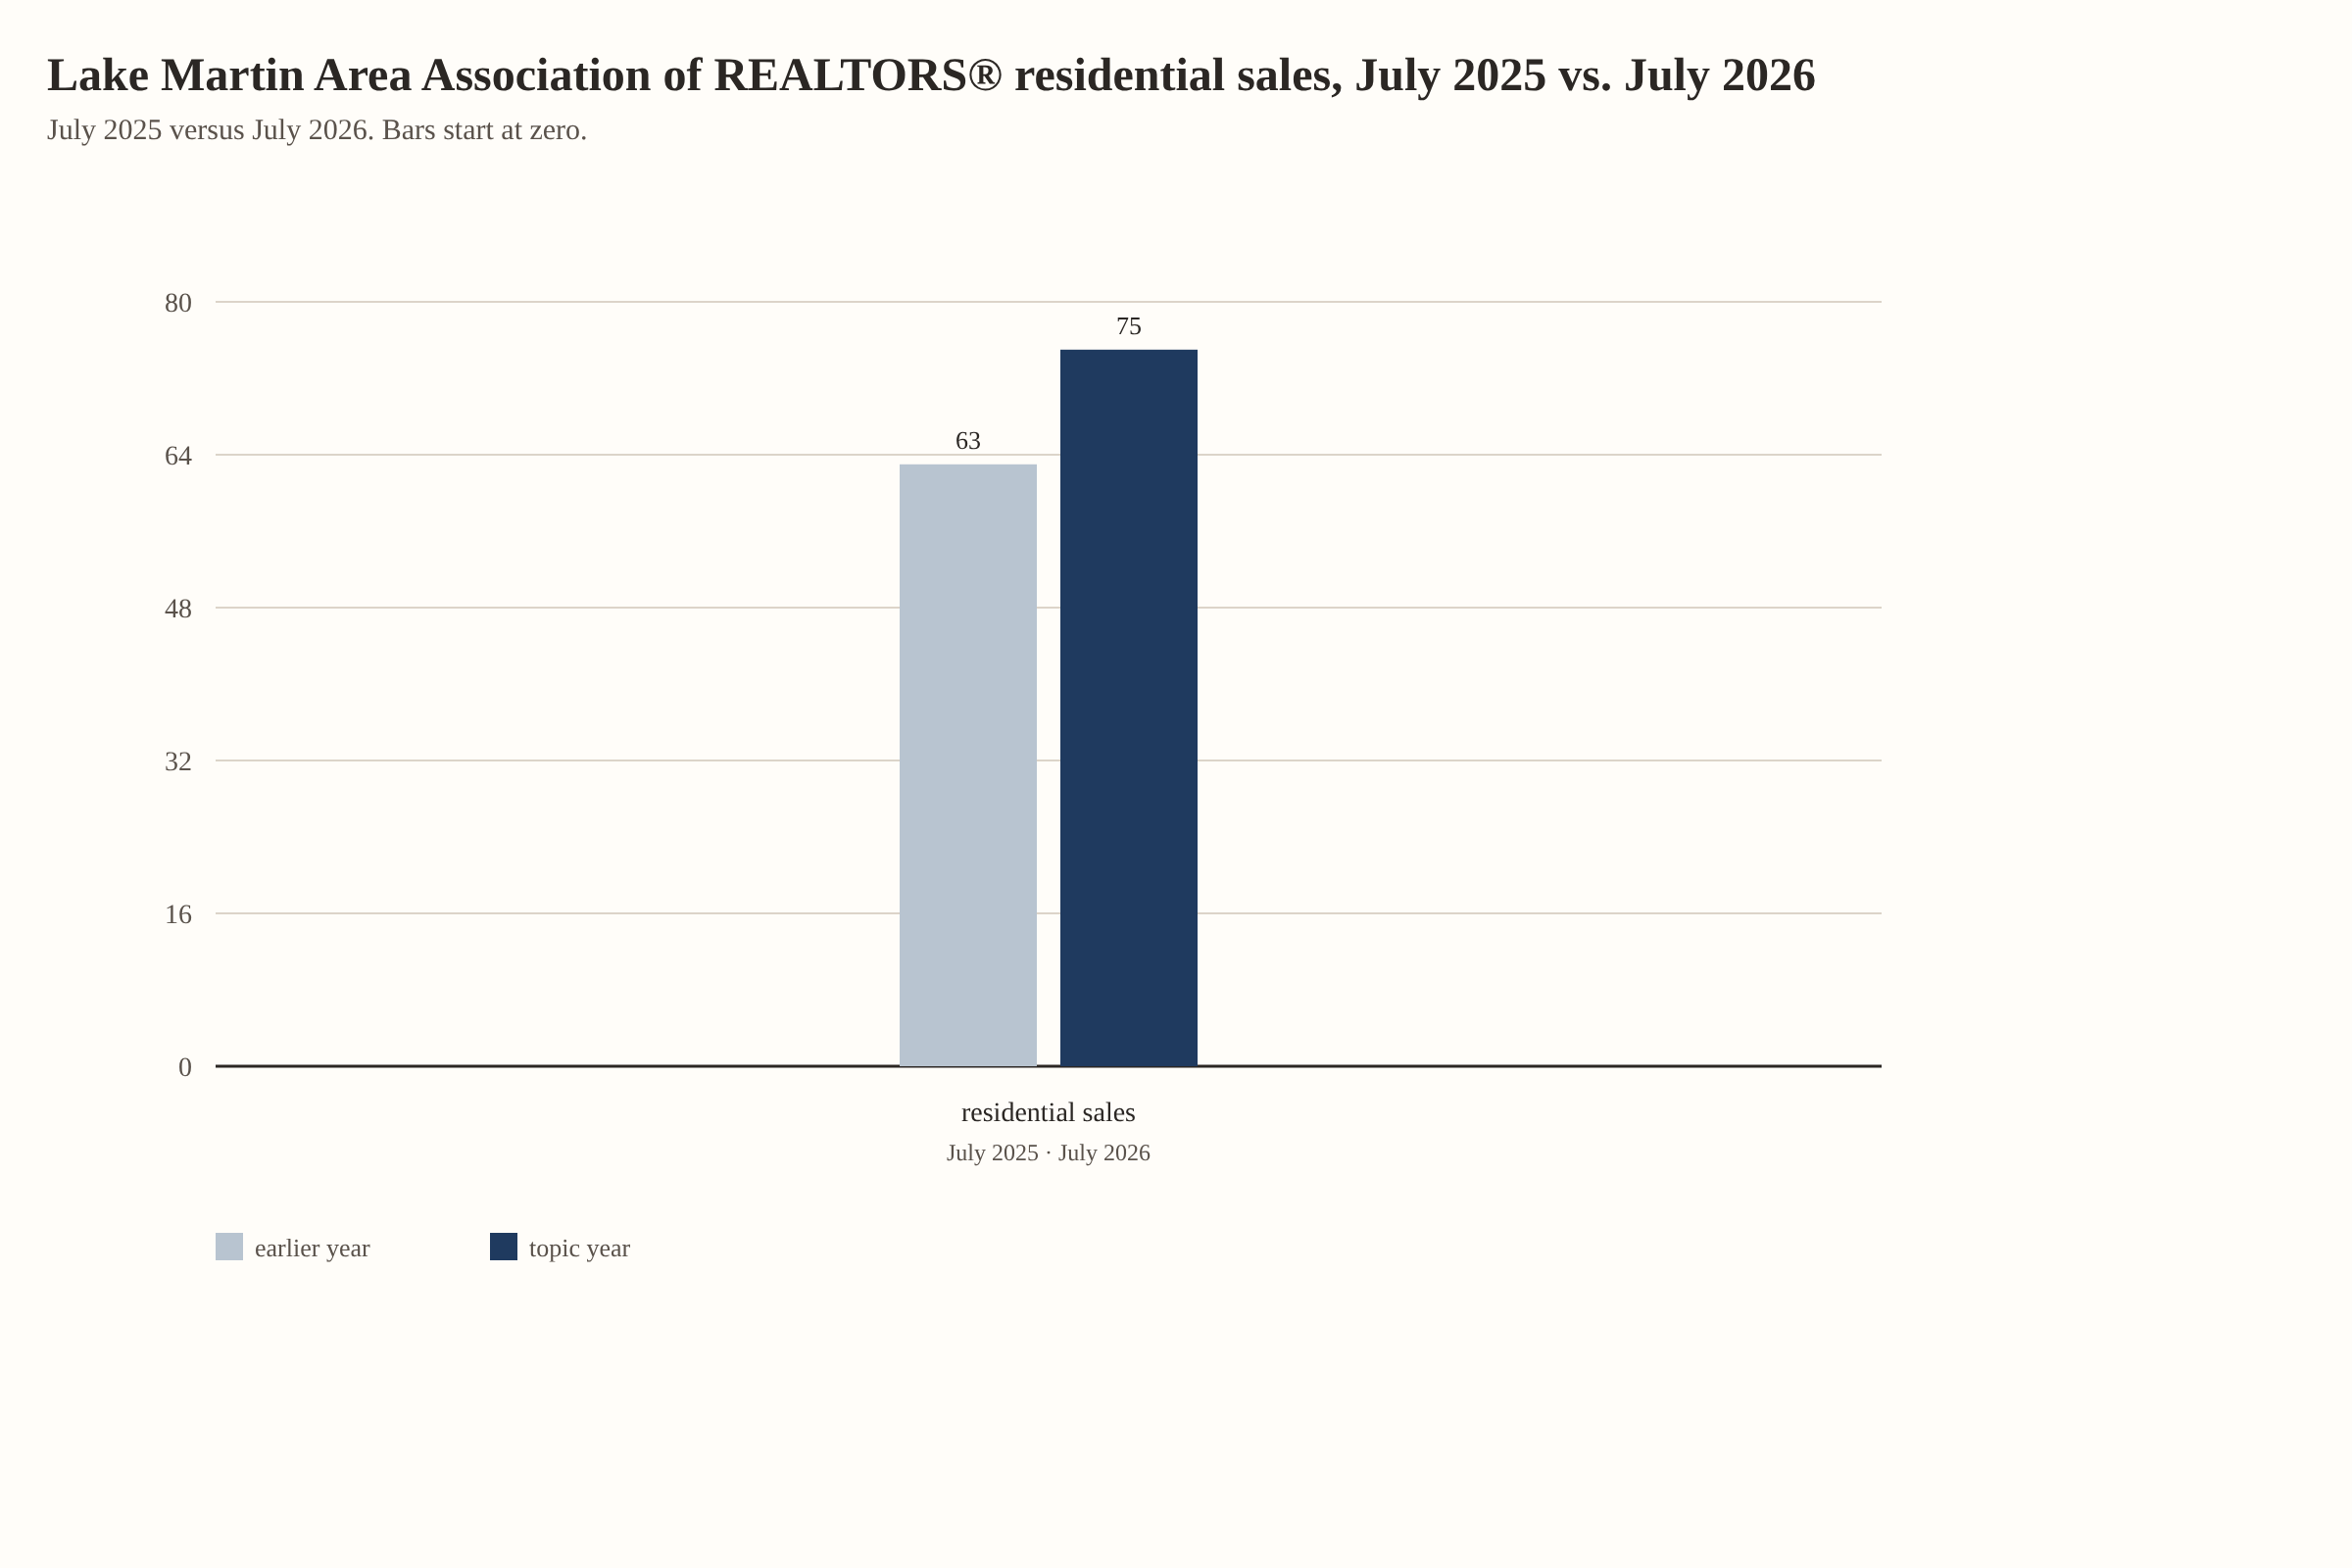
Chart 1. Lake Martin Area Association of REALTORS® residential sales, July 2025 vs. July 2026. Source: Lake Martin Area Association of REALTORS, July 2025; Lake Martin Area Association of REALTORS, July 2026.
What that tells me is that buyers were still closing on homes in the association-wide market in the heart of summer, and more of them than the summer before. A sales count is a demand signal, though, not a price signal. It says nothing about whether values rose, or whether your particular cove or community moved with the lake as a whole. LMAAR's own reports note that their accuracy depends on agents entering sold information, so I read these counts as directional.
Where you buy on the lake matters as much as when. If you're still narrowing that down, my rundown of the best Lake Martin communities walks through how different parts of the lake feel and what each offers.
The lake is the scarce part
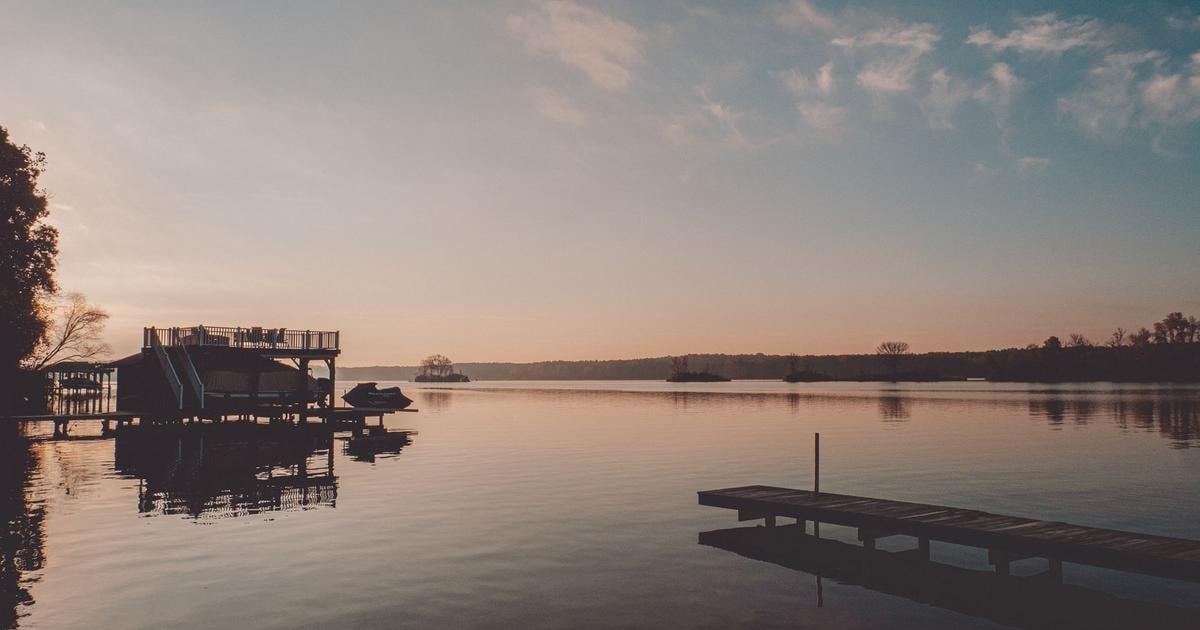
This is the piece of the investment case I believe in most. Lake Martin is a fixed amount of water. Alabama Power's Shorelines site lists the lake at 41,150 acres with 880 miles of shoreline and a full pool elevation of 491 feet, and Martin Dam has been in service since 1926, per Alabama Power Shorelines. The lake spans Tallapoosa, Elmore, and Coosa counties, per Wikipedia's Lake Martin entry.
Nobody is making more shoreline. That's why, in my experience, the lot and the water in front of it matter more than the kitchen. You can renovate a kitchen. You can't move a dock into deeper water. Here's what I look at before I ever open a cabinet:
- Water depth at the dock, and what that spot looks like when the lake sits below full pool in the winter months.
- Main channel or cove. Big-water views come with more boat traffic. Coves are quieter, with less open water in front of you.
- Which way the lot faces and what you actually see from the porch at sunset.
- The walk from house to shoreline. You'll make that trip with every cooler, float, and life jacket, so a gentle slope is worth real money.
- What's permitted for docks and shoreline changes on that lot. Confirm it before you close, not after.
These are also the features that shape resale. If you want a preview of how that plays out at the other end, my guide to selling waterfront property on Lake Martin covers what buyers look for when a lake house hits the market.
Financing costs more than it did a year ago
If you're financing, the carry matters as much as the price. Freddie Mac's 30-year fixed-rate average was 6.95% for the week of September 17, 2026, up from 6.76% the week before and 6.26% a year earlier, per the Primary Mortgage Market Survey. That's 0.69 percentage points higher than a year ago, by our math. Those are national weekly averages, and your own quote on a lake property will depend on your lender and your situation.
My read: a higher rate doesn't make a lake house a bad buy, but it makes the use value count for more. If this is where your people land every summer, the rate is part of the price of that. If the plan depends on rental income covering the note, a bigger payment leaves less room for a slow season.
How you use it changes the taxes
Two tax questions come up early with almost every lake buyer I talk to. I'm not your CPA (thank goodness for both of us), so take these to one, but know the rules exist before you make an offer.
Federal: personal use versus rental
Under IRS Topic 415, the IRS treats a home as a residence if your personal use is more than the greater of 14 days or 10% of the days you rent it at a fair rental price. And if you use the home as a residence and rent it for fewer than 15 days, you don't report that rental income and don't deduct rental expenses. That second rule is worth knowing if you only plan to rent the place for a big weekend or two a year.
Alabama: property tax class
The Alabama Department of Revenue assesses "single-family owner occupied residential property" as Class III at 10%, while "all property not otherwise classified" is Class II at 20%. ADOR's own example takes $100,000 in value at 10%, which is $10,000 assessed, and applies 32.5 mills for a $325 tax bill. Run that same example at 20% and it comes to $650, by our math. The 32.5 mills is ADOR's illustration, not a Lake Martin millage rate.
How a lake second home or a rental gets classified is a question for the revenue commissioner in the county where the house sits. Ask before you build your budget, because the class you land in changes your yearly carrying cost.
If you plan to rent it
Rental income is where lake-house math gets optimistic fast. My read is to treat rent as something that offsets your costs, not something that covers them, until you've owned the place through a full year and seen the real calendar.
Taxes come off the top. Alabama's state lodgings tax is 4% in Tallapoosa, Elmore, and Coosa counties, which aren't on the state's higher-rate county list. Counties and cities can add local lodgings taxes ranging from 1% to 13%, and stays of 180 continuous days or more are excluded, per the Alabama Department of Revenue's lodgings tax page.
Rules depend on exactly where the house is. Check which county it's in, whether it falls inside the limits of a town such as Dadeville or Alexander City, and read any community covenants for rental limits before you count on a single booking. If you're comparing a lake rental with one closer to campus, my guide to Auburn short-term rental rules covers the in-town side.
Local rules change. Confirm current requirements with the county or city where the house sits before relying on anything here. This is not legal advice.
How I'd judge a specific Lake Martin house
When a buyer asks me whether a particular listing is a good investment, these are the questions I walk through with them:
- Would you use it enough to love it even if it never went up in value?
- Can you carry the payment, property tax, insurance, and upkeep without any rental income?
- Is the lot the kind future buyers will want: usable water, a solid dock, a view worth sitting with?
- Do you have an off-season plan, including winter water levels, maintenance, and someone to check on the place?
- If you'll rent it, have you priced in lodgings taxes and confirmed the local rules?
If the answers are yes, the house is probably a good investment in the sense that matters most. If you're weighing lake life against keeping a base in a bigger city, my cost of living comparison for Auburn, Atlanta, and Birmingham can help frame the budget side of that decision.
So, is a Lake Martin house a good investment?
My honest answer: it's a strong investment in a life you want to live, and the finite shoreline gives good lots real staying power. It is not a guaranteed return. Sales were up this July compared with last July, financing costs more than it did a year ago, and your tax picture depends on how you use the house. Buy the lot and the water first, budget without the rent, and let any appreciation be the bonus.
Figures are closed data for the Lake Martin Area Association of REALTORS® market as of July 2026, from the Lake Martin Area Association of REALTORS®. Market conditions change and past figures are not a prediction.
Nothing here is legal, tax, or lending advice. Rates shown are national weekly averages and are not a quote, an offer of credit, or a prediction. For terms on your own situation, talk to a licensed lender.
This is not investment or tax advice and no return is guaranteed.
I'm Amy Cotney, REALTOR®, a licensed real estate salesperson (Alabama license #108235) with Roots Real Estate - Investment Development in Auburn, and helping people find their place on Lake Martin is some of my favorite work. If you're thinking about buying at the lake, get to know me and how I work, then call or text me at (334) 332-4002. I'd love to walk a few docks with you.
Sources
- Freddie Mac, Primary Mortgage Market Survey: https://www.freddiemac.com/pmms
- Alabama Power Shorelines, Lake Martin: https://apcshorelines.com/lake/martin/
- Wikipedia, Lake Martin: https://en.wikipedia.org/wiki/Lake_Martin
- IRS, Topic 415, Renting residential and vacation property: https://www.irs.gov/taxtopics/tc415
- Alabama Department of Revenue, Property Tax Assessment: https://www.revenue.alabama.gov/property-tax/property-tax-assessment/
- Alabama Department of Revenue, Lodgings Tax: https://www.revenue.alabama.gov/tax-types/lodgings-tax/
- Lake Martin Area Association of REALTORS, July 2026. Current report: https://www.lmaar.org/
- Lake Martin Area Association of REALTORS, July 2025. Current report: https://www.lmaar.org/