Updated October 2026
If a postcard, a text, or a mailer has offered to buy your Auburn house for cash, as-is, on your timeline, you're probably wondering whether it's worth a call. My honest answer: sometimes. A cash sale can make sense when a certain date, privacy, or skipping repairs matters more to you than the last dollar. It makes a lot less sense when you sign before comparing it with a real listing plan.
The Bottom Line
- "Cash buyer" covers very different businesses: iBuyers, local investors, wholesalers, and people buying a home to live in. They don't work the same way.
- Opendoor advertises cash offers anywhere in Alabama, but whether your Auburn house qualifies comes down to an address check. Offerpad doesn't list Alabama.
- The AUBURN reporting column showed more residential homes for sale and a higher median sold price in July 2026 than in July 2025; weigh a listing plan using current comparable homes.
- Compare final written cash terms, not a preliminary number, with an itemized listing net sheet.
- Have an Alabama real estate attorney read any contract that lets the buyer assign it to someone else.
Four kinds of "cash buyer," and why it matters who's on the other side
iBuyers. These are companies that make an online offer, buy the house themselves, and typically resell it. Opendoor is one example. It says it builds offers from comparable sales, local market data, and details about your home, and that its offer "is binding once you sign," while you "can walk away at any point before signing."
Local investors. An investor buying for its own account plans to renovate, rent, or resell. It's a principal in the deal, not your agent, so its job is to buy well, not to get you the highest price.
Wholesalers. This is the one to understand before you sign anything. Ask whether the buyer plans to close on your single-family home or find another buyer and assign the contract for a fee. Who would take title, and what would you receive in writing before any marketing or assignment? Have an independent Alabama real estate attorney review the proposed arrangement and current requirements before you sign.
Cash buyers who plan to live there. Some people simply pay cash for the house they'll live in. They usually shop the open market like anyone else, just without a lender. Selling to one of them is still a regular sale, often through a listing.
Who actually buys homes in Auburn for cash?
Opendoor's Alabama page says it "serves markets statewide across Alabama" and that "you can get a cash offer on your home anywhere in Alabama." The markets it names are places like Birmingham, Huntsville, Mobile, Montgomery, and Tuscaloosa. Auburn isn't on that list, so the only real test is entering your address and seeing what comes back.
Offerpad's locations page lists the states where it buys homes, and as of October 2026 Alabama isn't one of them.
Then there are the local "we buy houses" signs and mailers. I'm not naming any, because who's active changes and a business filing doesn't tell you whether a buyer can actually close. If one calls you, ask who will sign the contract, whether that party will take title or assign the deal, and which title company will handle closing.
Auburn's open market: July 2025 versus July 2026
Here's the alternative you're weighing a cash offer against. Per the Lee County Association of REALTORS®, the AUBURN column showed 442 residential homes on the market in July 2026, up from 320 in July 2025. New listings rose from 117 to 147, while sales fell from 136 to 114. By our math, that's 38.1% more homes on the market and 16.2% fewer sales than a year earlier.
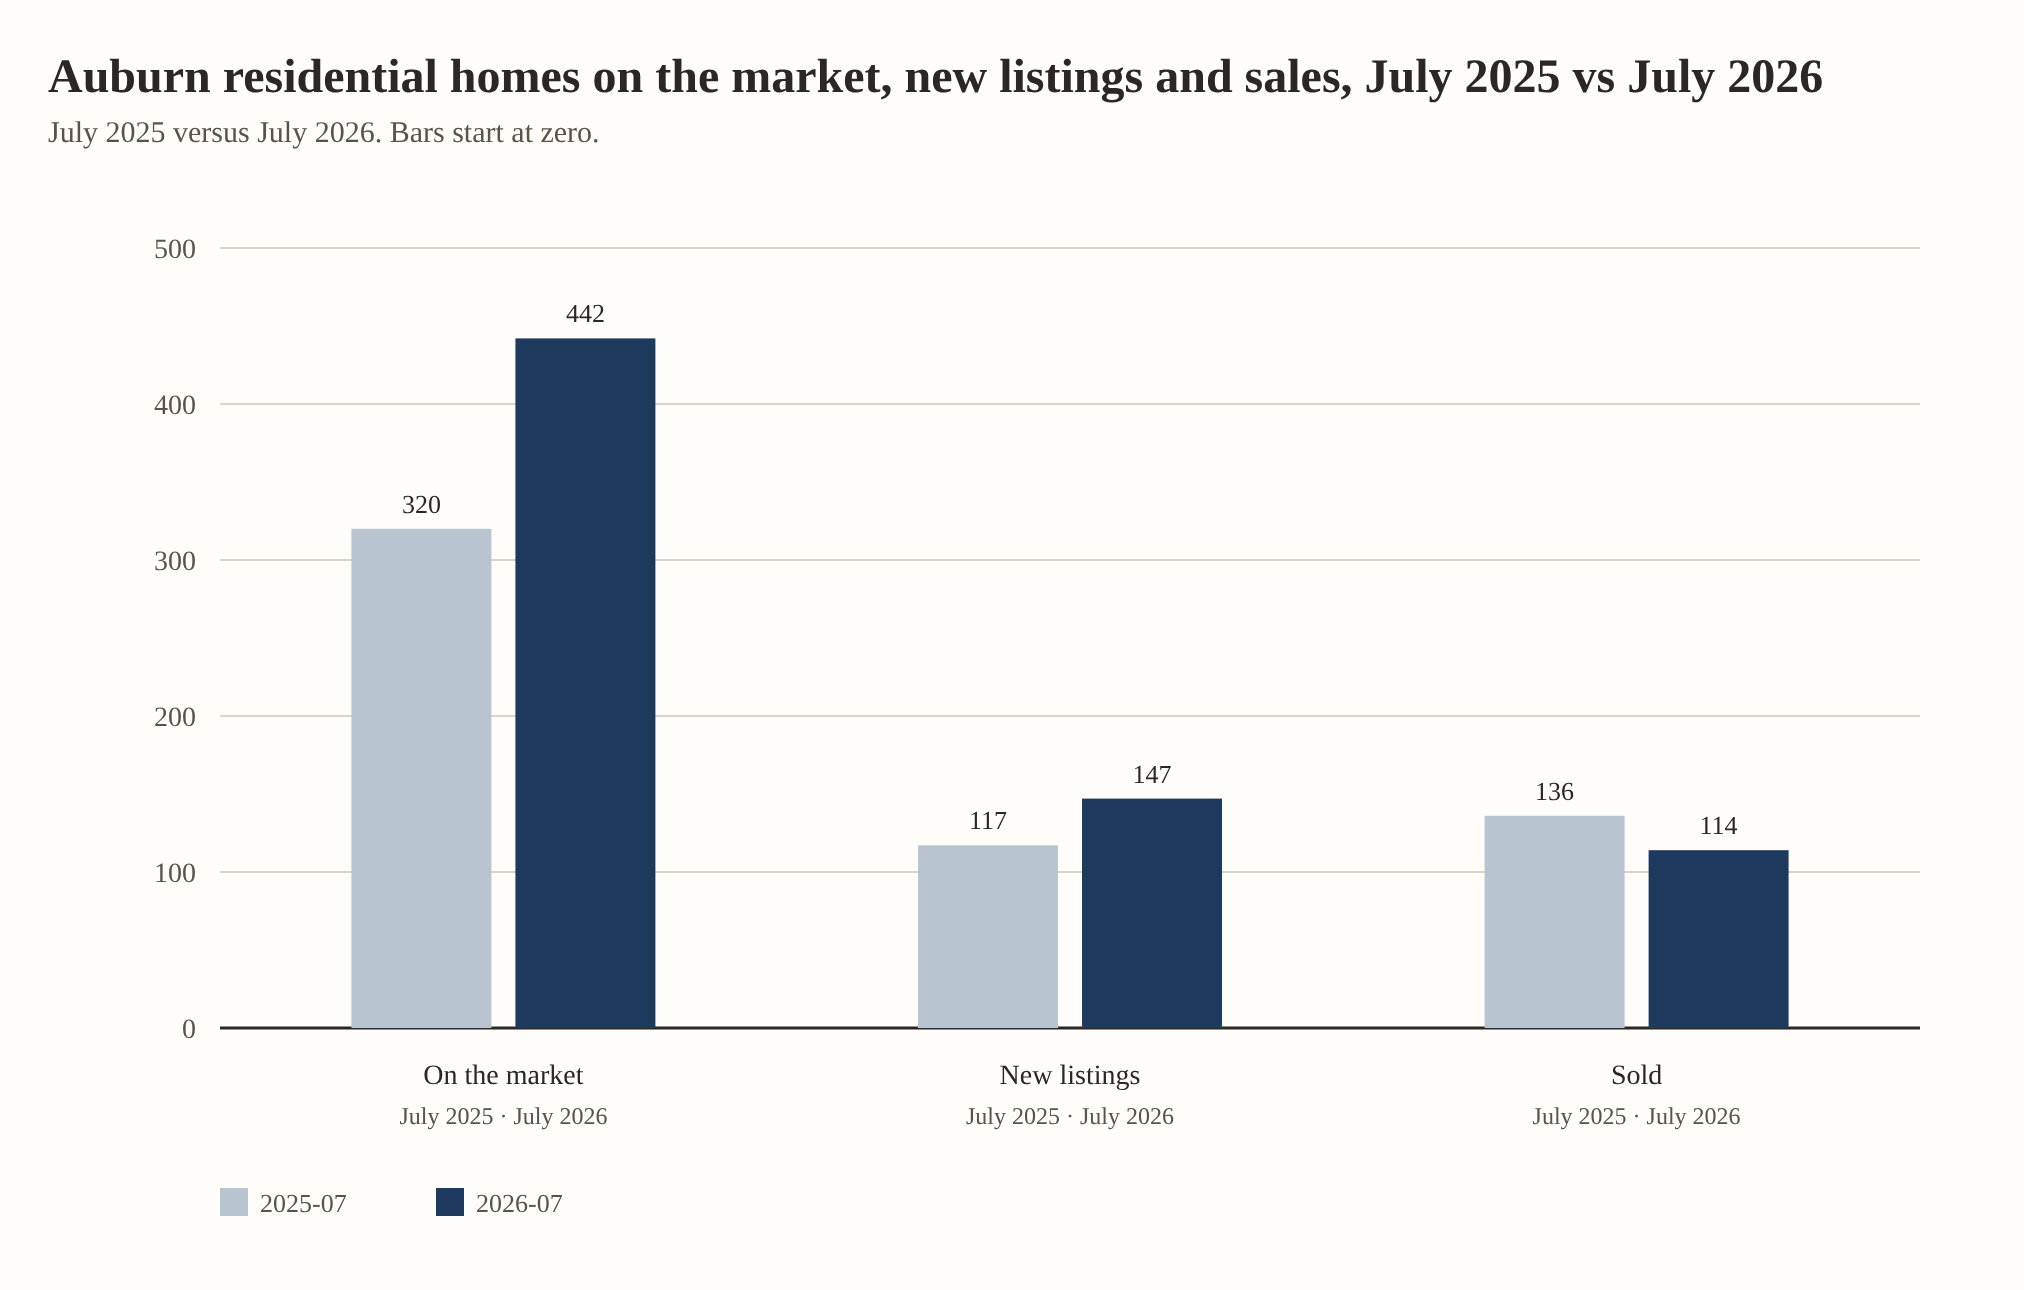
Chart 1. Auburn residential homes on the market, new listings and sales, July 2025 vs July 2026. Source: Lee County Association of REALTORS® monthly housing statistics, AUBURN column, July 2025; Lee County Association of REALTORS® monthly housing statistics, AUBURN column, July 2026.
Prices held up through that shift. According to the Lee County Association of REALTORS®, Auburn's median residential sold price was $494,087 in July 2026, compared with $431,625 in July 2025, up 14.5% by our math. Existing homes, the resale houses most sellers own, averaged 47 days on market in July 2026 versus 46 a year earlier. Existing-home sales came in at 68, down from 80.
My read: listing remains worth comparing with a cash offer. The July 2026 figures showed more total inventory than July 2025, but they don't tell us how many homes were move-in-ready. These are figures for the AUBURN reporting column, not a valuation of your house or a current October market snapshot. For that, start with what your Auburn home is actually worth or request a home valuation. Online home value estimates are a starting point only and are not a formal comparative market analysis or appraisal.
Figures are listing and closed data for the AUBURN column as of July 2025 and July 2026, from the Lee County Association of REALTORS® monthly housing statistics. Market conditions change and past figures are not a prediction.
How to compare a cash offer with listing
Start with the right cash number. Opendoor's Alabama page says it sends "a preliminary cash offer within 24 hours," then a walk-through where it "adjusts the offer based on any repairs needed." Its service charge "varies and is shown in your offer breakdown," and if repairs are needed, it "deducts the estimated cost from your proceeds." So "no repairs" means you don't manage contractors. It doesn't mean the repairs are free.
Then build both columns of a net sheet with the same line items, only where they actually apply:
- Date-specific mortgage payoff estimates for each scenario's expected closing date, reflecting accrued interest and any principal payments before closing
- Prorated property taxes and any credits
- Repair deductions on the cash side, or repairs and buyer concessions on the listing side
- Service charges or agent compensation, whatever your actual written agreements say
- Closing charges
- Nonrecoverable carrying expenses through each scenario's closing date, including the cash sale: mortgage interest, utilities, insurance, and upkeep, without duplicating interest included in payoff. Track pre-closing principal payments separately and reconcile them with the reduced payoff so principal is counted only once.
Two mistakes I'd steer you away from. Don't compare a preliminary cash quote with a gross list price, and don't leave a cost off one side because it makes the other look better. Compare final written cash terms with a realistic listing price, and treat what you can't pin down yet as unknown, not zero. My post on how to price your Auburn home walks through the listing side.
Speed and certainty: what cash changes and what it doesn't
Opendoor advertises "Close in as few as 21 days" and lets sellers choose a date "21 to 60 days out." Those are advertised timelines, not a promise for your address.
A genuinely funded cash purchase avoids reliance on a buyer's mortgage, but you still need to verify available funds and the buyer's ability to perform. It doesn't remove the assessment or repair deductions, and it doesn't fix title problems. A lien, an estate that isn't settled, or a boundary issue still has to be cleared before anyone can close. A signed cash contract can also carry its own contingencies, so read them as closely as you would on any offer.
When a cash sale can make sense
I'm not anti-cash. A seller can make a perfectly rational choice to take less in exchange for less work, a set date, or more certainty. My take is that it tends to fit when:
- A firm date matters more than top dollar. A job transfer, a purchase elsewhere, or an estate with a deadline. If you're managing it from afar, my guide to selling your home from out of state may help too.
- The house needs work you can't fund or oversee, and you've compared the repair deduction with what those repairs would actually cost. Here's what's worth fixing before you sell in Auburn.
- Privacy is worth real money to you. No showings, no open houses, no neighbors wandering through your closets.
- You've got final written terms in hand and a realistic listing net sheet beside them, and the gap is a price you're willing to pay for convenience.
It usually doesn't fit when you haven't compared, when the buyer's plan is to assign your contract, or when someone is rushing you to sign today. Request enough time for independent attorney review, and confirm the offer's expiration and any extension terms in writing.
What to check before you sign
- Close or assign? Ask directly: will the buyer take title or market and assign the contract? What written notice would you receive, when would you receive it, and does the contract require your consent? Have an independent Alabama real estate attorney review the assignment terms and current requirements before you sign.
- Licenses. If anyone in the deal says they're a real estate licensee, verify it with the Alabama Real Estate Commission. An investor buying for itself may not need a license at all, so ask what role each person is playing.
- Proof of funds and a real title company. Confirm who's holding the money and who's closing.
- Wire instructions. Never follow payment or wiring instructions from an email alone. Call the title company at a number you already have and confirm them by voice.
- "As-is" language. Ask your attorney what an as-is clause does and doesn't change about your disclosure duties in Alabama.
- Foreclosure deadlines. A cash offer doesn't, by itself, stop a foreclosure or change your lender's timeline. Talk to your servicer and a HUD-approved housing counselor right away.
- Taxes. The tax rules are the same whether your buyer pays cash or borrows. The IRS says you may exclude the first $250,000 of gain, increased to $500,000 for a married couple filing jointly, if you meet the tests, including owning the home at least 24 months of the last five years. A tax professional can tell you whether you qualify.
The options in between
A cash offer and a full traditional listing aren't your only two choices. You can list as-is, priced for condition, and let open-market buyers (including cash buyers) compete. You can list with a firm closing window built into your terms. Or, if you're thinking about doing it yourself, my post on FSBO vs using an agent in Auburn lays out what that involves.
What I'd do is simple: get the cash offer in writing, then put a realistic listing plan beside it, line by line. You can find more answers to common selling questions in my Auburn home seller FAQ.
I'm Amy Cotney, REALTOR®, with Roots Real Estate - Investment Development here in Auburn, and I'm happy to sit down with your cash offer and a listing plan and go through both with you, no pressure either way. You can learn more about me or reach out here. I build strong relationships that lead to sold homes and happy buyers, through communication, not automation.
Sources
- Federal Trade Commission, announcement concerning Opendoor Labs, Inc., August 2022: https://www.ftc.gov/news-events/news/press-releases/2022/08/ftc-takes-action-stop-online-home-buying-firm-opendoor-labs-inc-cheating-potential-sellers
- Federal Trade Commission, refund announcement concerning Opendoor Labs, April 2024: https://www.ftc.gov/news-events/news/press-releases/2024/04/ftc-sends-nearly-62-million-refunds-sellers-deceived-online-real-estate-listing-service-opendoor
- Internal Revenue Service, Publication 523, Selling Your Home: https://www.irs.gov/publications/p523
- Opendoor, "Selling to Opendoor vs. a Traditional Home Sale" (updated May 2026): https://www.opendoor.com/articles/how-selling-to-opendoor-compares-to-a-traditional-home-sale
- Opendoor, Sell Your House in Alabama (accessed October 2026): https://www.opendoor.com/sell/alabama_other
- Offerpad, Locations (accessed October 2026): https://www.offerpad.com/locations/
- Lee County Association of REALTORS® monthly housing statistics, AUBURN column, July 2026
- Lee County Association of REALTORS® monthly housing statistics, AUBURN column, July 2025